During 14–20 September 2026 (UTC), the Privacy, ZKML & Secure AI segment gained 71.76% on a starting-market-cap-weighted basis. NEAR Protocol generated almost the entire headline result: its 88.34% starting weight and 79.75% return contributed 70.45 percentage points.
This was not a case of one leader hiding losses elsewhere. Nineteen of 21 coins rose, the median return of a typical asset was +8.67%, and the other 20 coins returned a weighted +11.24% after removing NEAR. The week therefore carried two signals: extreme index concentration and genuinely broad directional participation.
One result, two different signals
- Segment weighted return: +71.76%.
- Leader weight: NEAR held 88.34% of starting market capitalization.
- Leader contribution: +70.45 pp; all other assets added about +1.31 pp to the full index.
- Ex-leader return: +11.24% for the other 20 coins using their own weights.
- Breadth: 19 of 21 coins gained; the typical asset's median return was +8.67%.
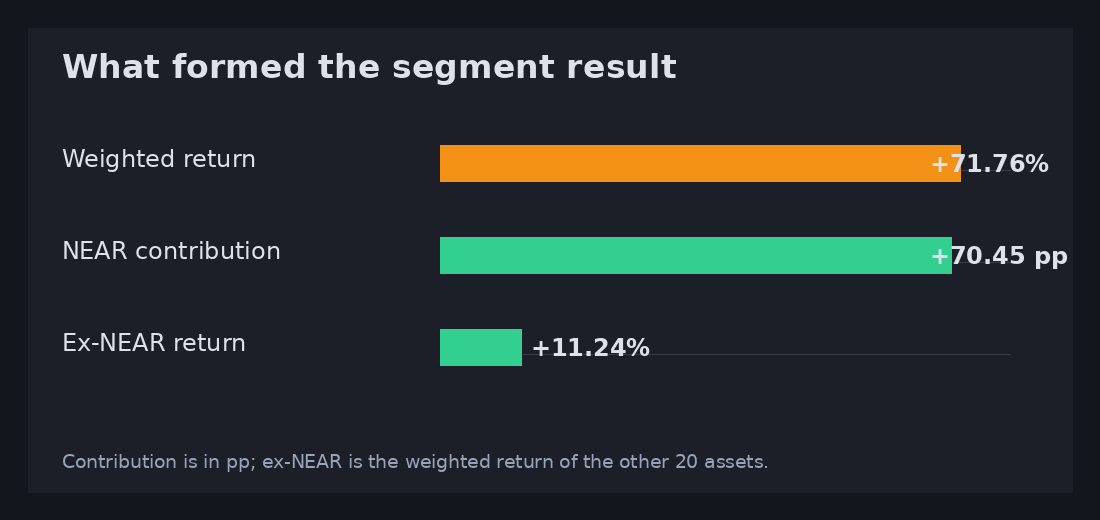
NEAR's contribution is measured in percentage points of the full index. Ex-NEAR return recalculates the other assets after removing the leader.
Why concentration did not erase breadth
The weighted index describes what happened to segment capital and largely followed NEAR because of its starting weight. Breadth and median answer a different question: how far the direction spread across constituents. Both show that the advance extended beyond one asset.
Only FLOCK (−3.32%) and TRUTH (−2.94%) declined. ARC (+154.98%), NIL (+53.33%), LAT (+52.28%), and PHA (+39.44%) were among the stronger gainers. Small assets materially affect breadth and the median, while barely moving the weighted index.
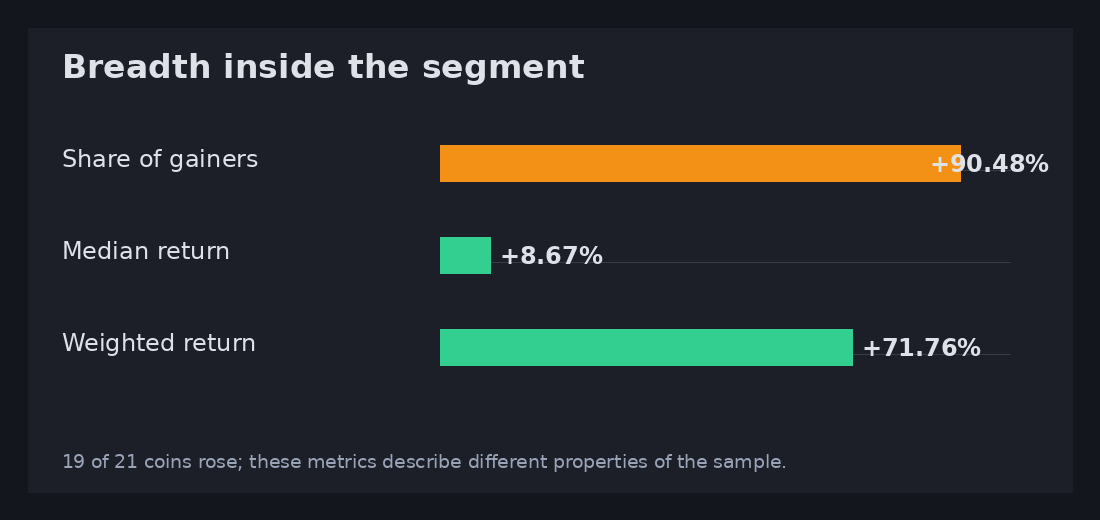
Breadth, median return, and weighted return measure different properties of the sample. They cannot be added or substituted for one another.
Constituents and auditable inputs
Membership was frozen on 21 September 2026 at 08:11 UTC. The first column provides each ticker and permanent CMC ID. Weight uses starting market capitalization; contribution equals weight × return. Display values are rounded, while the evidence pack retains full precision.
| Asset | Start market cap, $ | Weight, % | Return, % | Contribution, pp |
|---|---|---|---|---|
| NEAR (6535) | 3,006,725,689.00 | 88.34 | +79.75 | +70.446 |
| ROSE (7653) | 54,973,538.36 | 1.62 | +10.81 | +0.175 |
| ACU (36492) | 45,553,980.12 | 1.34 | +1.57 | +0.021 |
| FLOCK (34987) | 31,203,350.70 | 0.92 | -3.32 | -0.030 |
| TRUTH (38178) | 29,431,673.32 | 0.86 | -2.94 | -0.025 |
| VANA (34619) | 28,501,929.45 | 0.84 | +16.28 | +0.136 |
| RLC (1637) | 24,141,426.67 | 0.71 | +13.31 | +0.094 |
| FLUX (3029) | 23,250,798.36 | 0.68 | +5.56 | +0.038 |
| OPG (39800) | 22,719,740.18 | 0.67 | +13.89 | +0.093 |
| PHA (6841) | 22,606,756.62 | 0.66 | +39.44 | +0.262 |
| NES (30140) | 21,269,213.28 | 0.62 | +8.67 | +0.054 |
| NIL (35702) | 20,710,493.16 | 0.61 | +53.33 | +0.324 |
| FAI (34330) | 18,825,082.71 | 0.55 | +2.97 | +0.016 |
| NEWT (36861) | 14,662,225.77 | 0.43 | +3.14 | +0.014 |
| BLUAI (38717) | 13,768,907.48 | 0.40 | +1.37 | +0.006 |
| FHE (36153) | 10,797,632.01 | 0.32 | +10.11 | +0.032 |
| POND (7497) | 6,899,023.04 | 0.20 | +0.43 | +0.001 |
| LAT (9720) | 3,315,140.97 | 0.10 | +52.28 | +0.051 |
| ALEPH (5821) | 2,576,990.24 | 0.08 | +6.72 | +0.005 |
| ARC (13051) | 949,508.31 | 0.03 | +154.98 | +0.043 |
| ZKML (29445) | 782,173.53 | 0.02 | +3.63 | +0.001 |
| Total | 3,403,665,273.28 | 100.00 | +71.76 weighted | +71.756 |
The market helped, but did not explain the magnitude
The week was positive outside this segment as well. AI-sector market capitalization rose 28.20%, BTC price gained 6.13%, and total crypto market capitalization increased 6.78%. Privacy/ZKML exceeded the AI-sector change by 43.56 percentage points, but this spread is not automatically the return of an investable trading strategy.
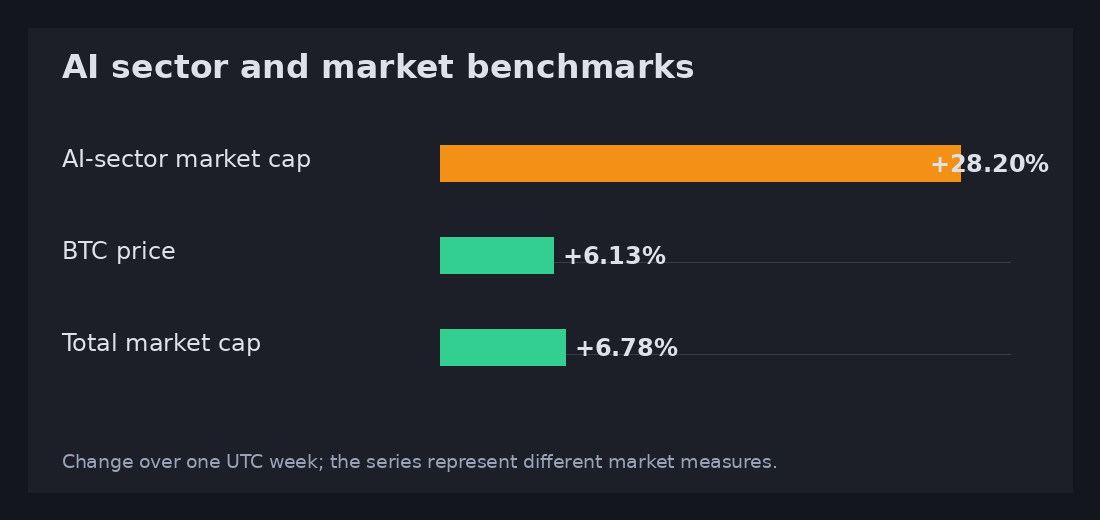
The comparison uses AI-sector capitalization, BTC price, and total market capitalization. These are different benchmark types, not identically constructed indices.
What the data does not prove
Official NEAR material explains the Confidential Intents architecture, while the public NEAR dashboard reports confidential TVL metrics. These sources support the project's privacy-infrastructure classification. They do not prove that those developments caused this week's price move.
Our data establishes concurrent movement and the structure of the result. A causal conclusion would require time-aligned announcements, volume, and market reaction; the weekly evidence pack does not establish that chain.
Method and limitations
The study covers 14–20 September 2026 (UTC). Coin returns use 13 and 20 September daily closes as boundary observations. Market benchmarks use exact snapshots at 00:00 UTC on 14 and 21 September. All 21 segment members had the required data, producing 100% coverage.
Coin daily records use providers retained in the evidence pack; market benchmarks come from internal_rollup. Return = (end price / start price − 1) × 100. Weight = starting market cap / total starting market cap. Contribution = weight × return. Median describes the typical asset, breadth is the share of positive returns, and ex-leader return is recalculated after excluding NEAR.
Source data pack: 54eac28199d28ca6. Segment membership was frozen when the pack was generated and does not reconstruct taxonomy retroactively.